
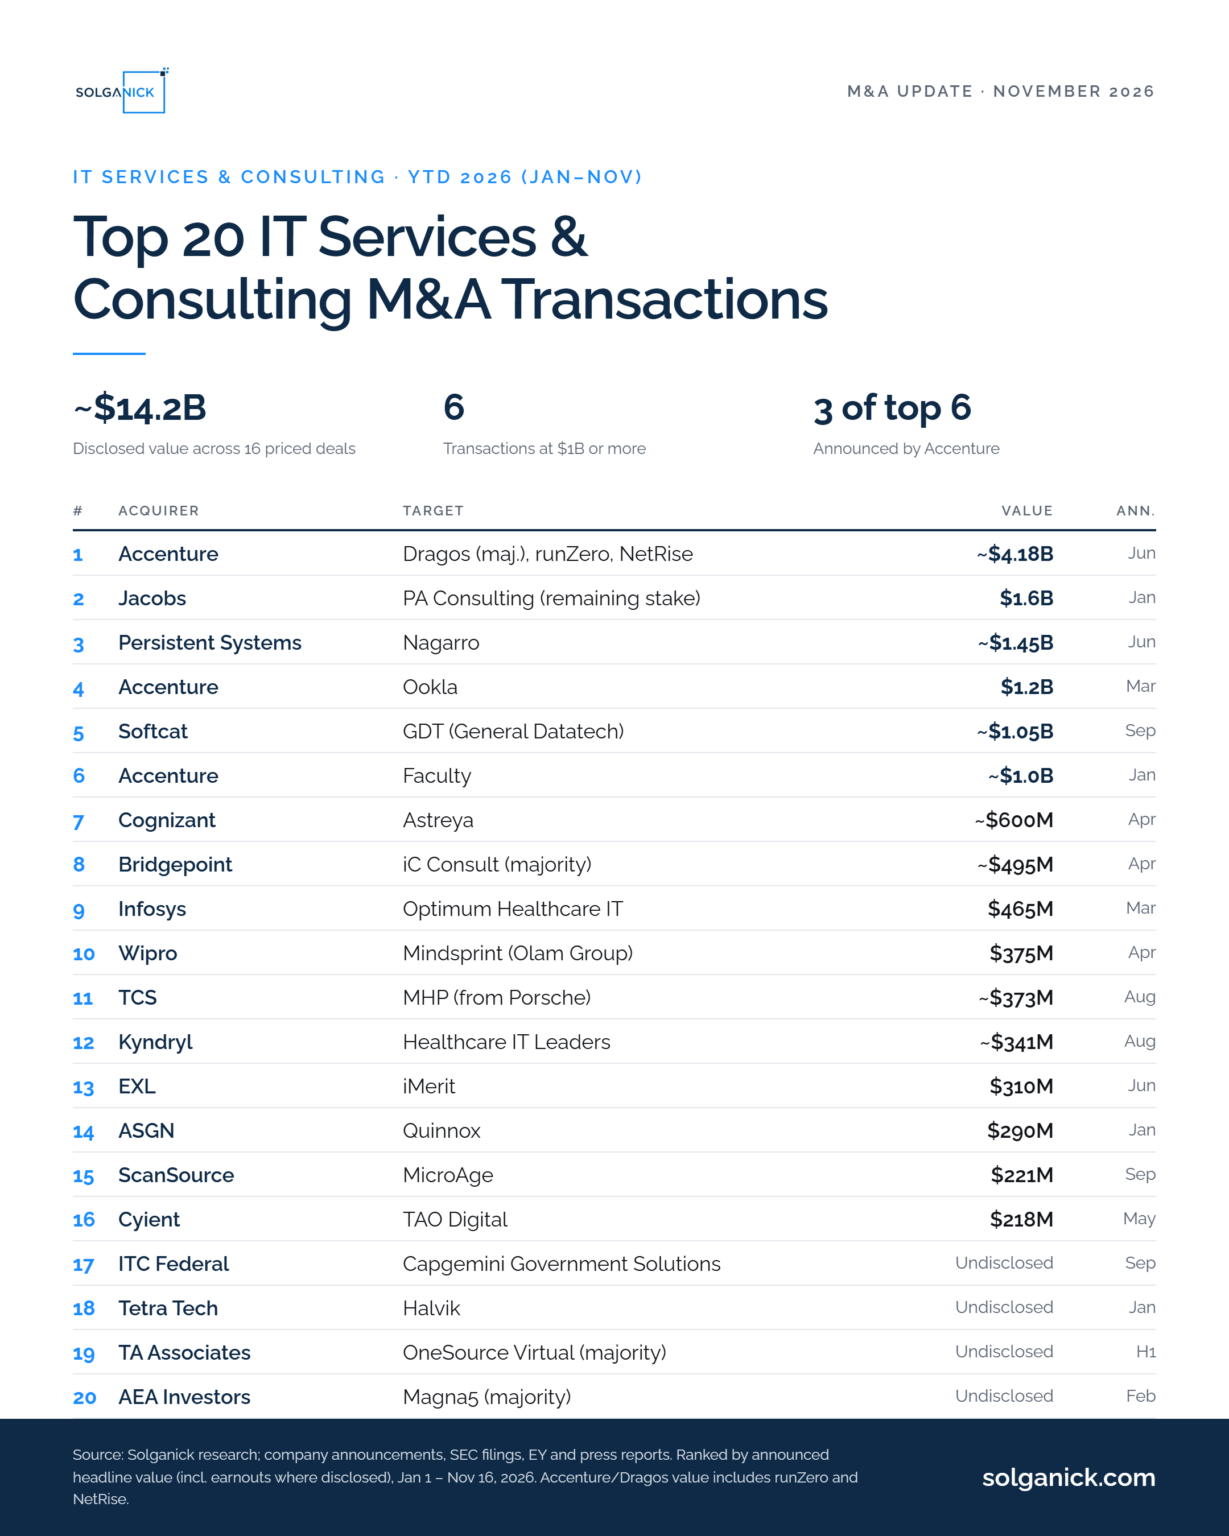
November 17, 2026 – Solganick has published its list of the Top 20 IT services and consulting M&A transactions announced year-to-date in 2026 (January 1 – November 16). The list covers acquisitions of systems integrators, IT consulting and digital engineering firms, managed services providers, and capability acquisitions by the largest IT services buyers.
The IT consulting and services M&A market saw approximately $14.2 billion in disclosed transaction value across 16 deals from January to November 2026, with six transactions exceeding $1 billion. Accenture was a leading acquirer, responsible for three of the largest deals, including Dragos, Ookla, and Faculty. While many transactions featured an AI narrative, buyers primarily sought vertical depth, delivery scale, and hyperscaler-aligned capabilities. Private equity firms also remained active, making platform-level investments in companies like iC Consult, OneSource Virtual, and Magna5.

Key Takeaways
- Roughly $14.2 billion in disclosed value across the 16 transactions with published pricing, with six deals at $1 billion or more.
- Accenture led the market, announcing three of the six largest transactions: Dragos (with runZero and NetRise), Ookla and Faculty. Its capability buys spanned OT cybersecurity, network intelligence and applied AI.
- Indian IT services firms moved up-market with scaled, client-relationship-driven deals, including Persistent–Nagarro, Infosys–Optimum Healthcare IT, Wipro–Mindsprint and TCS–MHP.
- AI is the headline, client access is the asset. Most large transactions carried an AI narrative, but buyers paid for vertical depth (healthcare, automotive, federal), delivery scale and hyperscaler-aligned capabilities.
- Private equity stayed active at the platform level, including Bridgepoint–iC Consult, TA Associates–OneSource Virtual and AEA Investors–Magna5, alongside continued MSP and cloud-partner roll-ups.
What methodology was used to compile the Top 20 IT Consulting and Services M&A Transactions list?
| # | Acquirer | Target | Deal Value | Announced |
|---|---|---|---|---|
| 1 | Accenture | Dragos (majority stake), runZero and NetRise | ~$4.18B | Jun 2026 |
| 2 | Jacobs | PA Consulting (remaining stake) | $1.6B | Jan 2026 |
| 3 | Persistent Systems | Nagarro | ~€1.27B EV (~$1.45B) | Jun 2026 |
| 4 | Accenture | Ookla (Ziff Davis Connectivity division) | $1.2B | Mar 2026 |
| 5 | Softcat | GDT (General Datatech) | ~$1.05B | Sep 2026 |
| 6 | Accenture | Faculty | ~$1.0B (reported) | Jan 2026 |
| 7 | Cognizant | Astreya | ~$600M | Apr 2026 |
| 8 | Bridgepoint | iC Consult (majority stake) | ~€450M (~$495M) | Apr 2026 |
| 9 | Infosys | Optimum Healthcare IT | Up to $465M | Mar 2026 |
| 10 | Wipro | Mindsprint (Olam Group) | $375M | Apr 2026 |
| 11 | TCS | MHP (from Porsche) | €320M EV (~$373M) | Aug 2026 |
| 12 | Kyndryl | Healthcare IT Leaders | ~$341M | Aug 2026 |
| 13 | EXL | iMerit | Up to $310M | Jun 2026 |
| 14 | ASGN | Quinnox | $290M | Jan 2026 |
| 15 | ScanSource | MicroAge | $220.5M | Closed Sep 2026 |
| 16 | Cyient | TAO Digital | $218M EV | May 2026 |
| 17 | ITC Federal | Capgemini Government Solutions | Undisclosed | Sep 2026 |
| 18 | Tetra Tech | Halvik | Undisclosed | Jan 2026 |
| 19 | TA Associates | OneSource Virtual (majority stake) | Undisclosed | H1 2026 |
| 20 | AEA Investors | Magna5 (majority stake) | Undisclosed | Feb 2026 |
Transaction Highlights
- Accenture / Dragos, runZero and NetRise (~$4.18B). A majority stake in OT cybersecurity platform Dragos plus full ownership of runZero and NetRise, building an industrial and critical-infrastructure security practice.
- Jacobs / PA Consulting ($1.6B). Jacobs agreed to buy the remaining stake it did not already own, valuing PA at approximately £3.05 billion, or about 13.0x expected 2025 adjusted EBITDA before synergies.
- Persistent Systems / Nagarro (~€1.27B EV). An all-cash public takeover offer at €81 per share, creating a combined AI-led digital engineering group with roughly $2.9 billion in revenue run-rate and a much larger European footprint.
- Accenture / Ookla ($1.2B). The acquisition of Ziff Davis’s Connectivity division (Speedtest, Downdetector, Ekahau, RootMetrics), which generated about $231 million of 2025 revenue.
- Softcat / GDT (~$1.05B). UK-listed Softcat’s entry into the U.S. market through the purchase of Dallas-based GDT from H.I.G. Capital.
- Cognizant / Astreya (~$600M). Adds AI infrastructure and data center managed services as hyperscaler capital spending accelerates.
- Wipro / Mindsprint ($375M) and TCS / MHP (€320M). Both acquisitions were paired with large multi-year services contracts from the seller (Olam Group and Porsche, respectively), a structure we expect to see more often.
Methodology
Transactions are ranked by announced headline value for deals announced between January 1 and November 16, 2026. Values reflect enterprise value or total consideration as reported, including earnouts and contingent consideration where disclosed; non-USD values are converted at approximate rates. Positions 17–20 are notable transactions with undisclosed terms, selected by target scale. The list includes product and data businesses (Dragos, Ookla, iMerit) acquired by IT services firms, consistent with how the sector’s buyers are deploying capital. Coforge’s $2.35 billion acquisition of Encora is excluded because it was announced in December 2025.
About Solganick
Solganick is a data-driven investment bank and M&A advisory firm focused exclusively on the software and IT services sectors, including cloud, cybersecurity, SAP/ERP, managed services and AI consulting. Since 2009, we have advised founders, management teams and private equity sponsors on sell-side and buy-side transactions.
For more information or to discuss an M&A opportunity, please contact us.